Build an approval‑ready credit profile
Understand what’s driving your credit decisions, identify items that may be unfair or inaccurate, and take a structured next step toward stronger approvals and better terms.
Built around established U.S. credit reporting practices and dispute procedures under the Fair Credit Reporting Act (FCRA). No unrealistic promises—just clarity, documentation, and structured credit improvement.
Unlock more options
Choose the outcome you care about. We’ll outline what improves it—and what to watch for—so you can move forward with confidence.
Your path to stronger credit
A stronger credit profile can mean better approval odds, improved loan terms, and more financial flexibility. Get a clear, no-fluff overview of what credit improvement can help you achieve — then take the next step when you're ready.
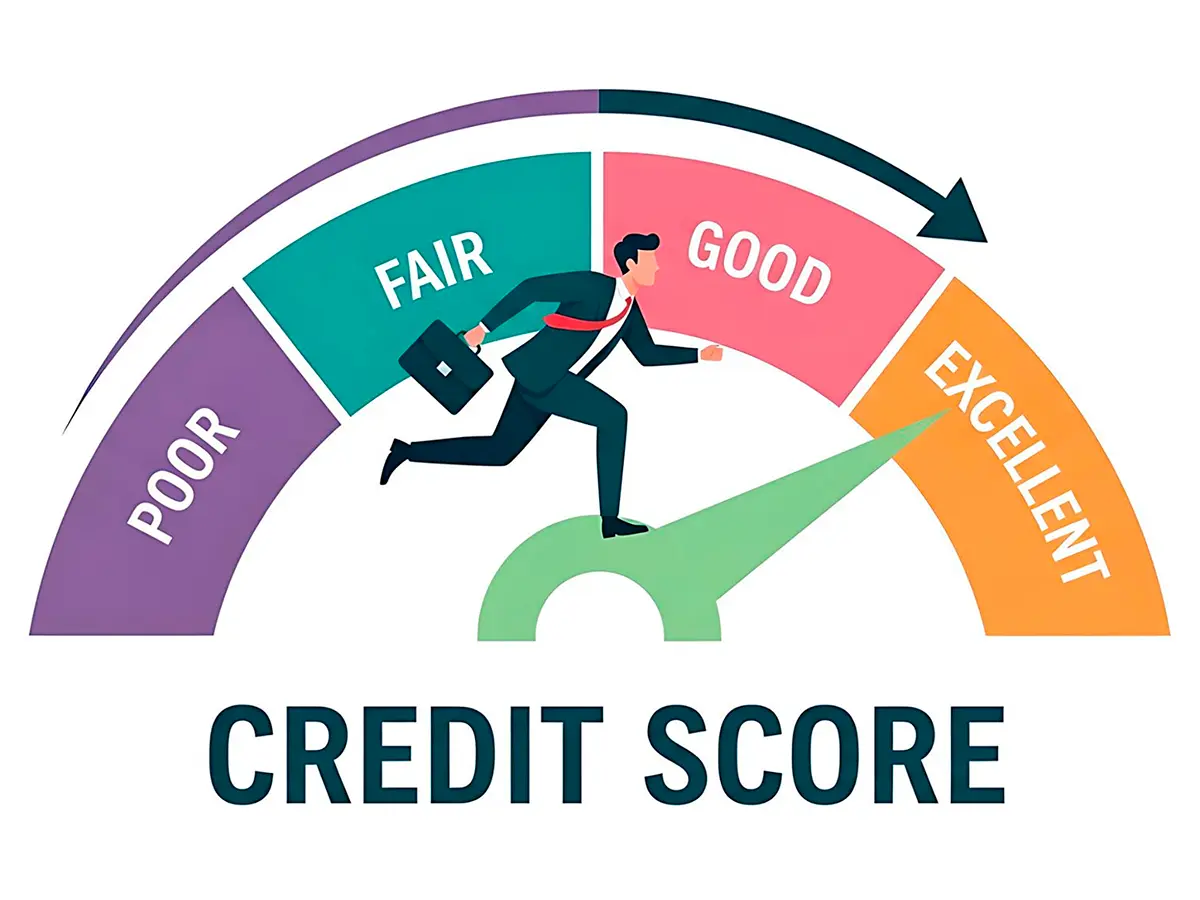
Credit decisions in the U.S. are typically influenced by payment history, utilization ratios, account age, recent inquiries, and the accuracy of reporting across major credit bureaus.
Even small inconsistencies can affect lending algorithms. A structured credit improvement approach focuses on verified data, responsible usage patterns, and consistent financial behavior.
*Results vary. This page does not guarantee outcomes.
How it works
A straightforward workflow used by reputable credit‑support programs: review, challenge what’s questionable, and build stronger habits while updates are processed.
Review your starting point
Clarify your goal and look at what’s currently affecting approvals and terms.
Identify what can be challenged
See what information is typically needed, what to expect next, and how the workflow usually looks.
Move forward
Continue to explore available options and take the next step toward better credit outcomes.
credit repair wichita ks insights for flexible, high-performance rebuilding
See your finances as a system. In Wichita, credit isn't just a score; it's leverage for lower auto rates on Kellogg, more comfortable mortgage payments near Maize, and smoother capital access when you test a storefront idea in Old Town. Credit repair - done right - prioritizes accuracy, utilization, and steady momentum. It's not magic; it's a performance process with room to adapt as life shifts.
The local context that shapes outcomes
Local lenders and credit unions weigh debt-to-income and steady payment history, and they often look closely at recent late payments and revolving balances. Cost of living helps: it's easier to keep utilization low when budgets aren't constantly stretched. Big-picture view: focus on the inputs you control - clean data, disciplined cash flow, and strategic account management - and the score follows. Said another way, repair is less about deleting the past and more about engineering the next 90 days.
- Accuracy first: Verify every tradeline, balance, and late mark across Experian, Equifax, and TransUnion. Dispute genuine errors with documentation.
- Utilization as a lever: For maximum performance, keep individual and overall revolving use under 10% - ideally under 9% - especially on cards that report right after the statement closes.
- Momentum over drama: Autopay the minimum on time, then add targeted principal payments. Positive data points compound faster than big swings.
A flexible plan built for performance
- Days 0 - 7: Baseline and triage. Pull free weekly reports at AnnualCreditReport. List inaccuracies, high-utilization cards, and any collections. Create a simple tracker: creditor, account number (masked), issue, action, deadline.
- Days 10 - 30: Correct the record. Dispute errors with bureaus online or by mail; include statements, payment proofs, or identity documents as needed. Keep copies and note mail dates to manage the 30 - 45 day window.
- Days 30 - 60: Strategic negotiations. For valid collections, consider settlement options and request deletions when a collector's policy allows; if not, aim for "paid" plus clear receipts. For isolated late payments, try a goodwill letter - especially if you've since paid perfectly.
- Days 45 - 90: Utilization optimization. Time payments to post before statement dates. If income supports it, request prudent credit line increases or add a low-fee secured card at a local credit union to spread balances. A small share-secured installment can round out your mix without overspending.
- 90+ days: Sustain and expand. Keep autopay on, avoid closing your oldest card, and let average age grow. Build a three-month emergency buffer so a surprise bill doesn't become your next late.
A real Wichita moment
On a Tuesday lunch near Old Town Square, you check your app after a mailed dispute. A medical collection drops; your utilization is at 7% after mid-cycle payments. A prequalification from a Wichita credit union shows an auto rate two points lower than last spring. The difference covers your weekend roof repair - no new debt required.
Tools and metrics that matter
- Utilization: overall and per-card, checked before statements cut.
- Payment streak: on-time months since last late; protect this above all.
- Average age: keep legacy accounts open to preserve history.
- Derogatory timeline: track disputes and responses by date; document everything.
- Budget buffer: weekly cash-flow check to prevent surprise balances.
Options in Wichita - choose what fits
You can handle repairs yourself, pair DIY with nonprofit counseling for budgeting help, or hire a professional. Explore only what aligns with your capacity.
- DIY: Maximum control, minimal cost; requires organization.
- Nonprofit counseling: Useful for cash-flow structure and debt management plans.
- Fee-based pros: Look for transparent pricing, no wild guarantees, and month-to-month flexibility.
Think of credit repair as tuning a reliable truck: small, consistent adjustments create outsized performance. Reframed: it's a system you guide week by week, and Wichita's steady pace makes that cadence achievable.
More info about Kansas Credit Repair Biz. Map. 4925 S Broadway. Ste 1103. Wichita, KS 67216. Directions. (316) 313-5155. Call Now.
Wichita Credit Repair, Wichita, Kansas. 9 likes. CRE Credit Services is the top credit services and education company in the nation owned by credit e.
We do more than just improve your credit score by disputing inaccuracies. Our goal is to improve your credit knowledge, in order to help you achieve YOUR ...
Frequently asked questions
A clear next step — without the guesswork
See what’s impacting approvals and what may deserve a closer look.
Understand how disputes are structured and what documentation matters.
Improve utilization, consistency, and long-term credit stability.
See what improving your credit could change
Take a structured next step based on your current profile — and decide with clarity.